Canada's Income Tax Act has ballooned to more than a million words, experts say
The law has grown from 14 pages in 1917 to over 3,000 pages, with business leaders citing billions in compliance costs.
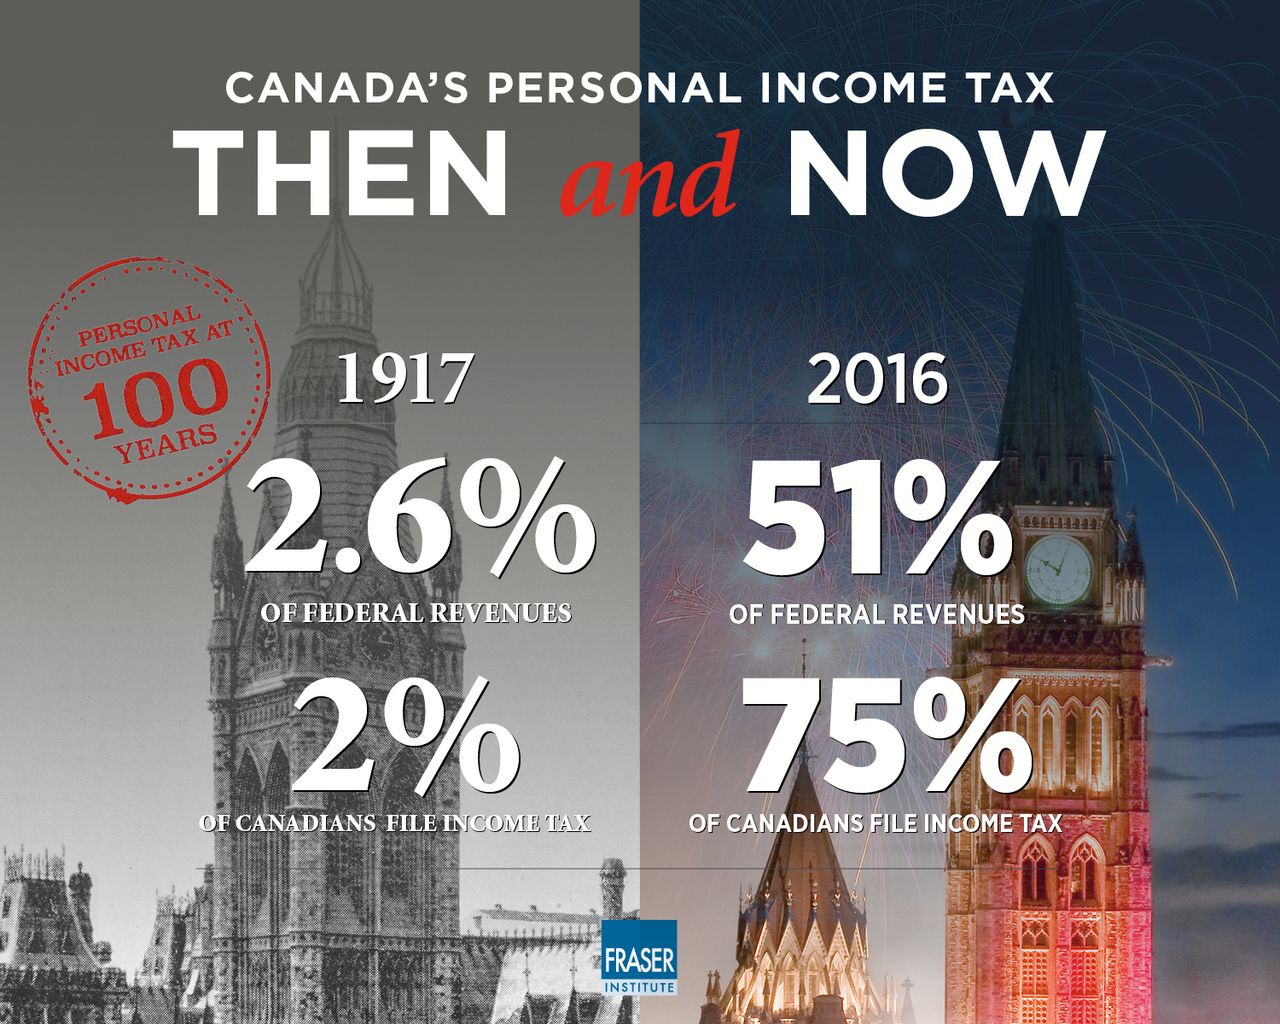
The federal Income Tax Act, once a 14-page pamphlet, now spans more than 3,000 pages and over one million words, a growth experts say imposes billions in compliance costs on businesses.
Steve Suarez, a partner at the law firm Borden Ladner Gervais, called the current system “a Frankenstein’s monster.”
“Over 50 years, we keep bolting on new pieces, new initiatives, new rules,” Suarez said. “Nothing ever comes off, just new stuff gets bolted on.”
READ MORE: Economists and executives urge sweeping tax reform to boost Canadian investment
READ MORE: Alberta suspends fuel tax for three months as rebate program falters
He said companies are spending more on lawyers, accountants and internal tax staff simply to comply, leaving small businesses adrift and households with higher bills.
“As a guy with 35 years of experience invested in the current system, I’ve got every incentive to keep the complexity,” he said. “But as a Canadian and as a father, I know we’ve got to do better than this.”
The original Income War Tax Act was introduced in 1917 to help finance the First World War, alongside the Military Service Act which forced conscription.
By the standards of what followed, that legislation was remarkably slight, no longer than a brochure you might find in a hotel lobby, according to the notes.
Research by François Vaillancourt, a professor emeritus of economics at the Université de Montréal, found that between 1971 and 2014, the physical area occupied by the Income Tax Act and its regulations increased 355 per cent.
Vaillancourt, who was asked by the late tax scholar Richard Bird to collaborate on research into the complexity of Canadian tax law, said they used three indicators to measure a problem that was widely talked about but difficult to show.
They measured the physical size of the income-tax code, the number of tax expenditures, credits, deductions, exemptions and other special treatments, and the length of the forms, guides and other documents taxpayers had to experience.
On its own, Vaillancourt said, measuring the physical area was an extremely dumb way to measure complexity. But the three measurements they used were highly correlated over time, he said.
None could say precisely how much more complex the system had become, but they pointed in the same direction. It obviously went up, Vaillancourt said.
A graduate student working with Vaillancourt discovered that at one point the book appeared to get considerably shorter, but this was because the publisher had changed the dimensions of the book, making it slimmer and wider.
The typography, already a strain on the eyes, was the same. I don’t think they could have gone to a smaller font, Vaillancourt recalled.
In more recent years, software and electronic filing have made it easier at the individual level to handle that complexity. Vaillancourt’s research suggests personal compliance costs have fallen even as the underlying tax system has continued to grow more complex.
For small-business owners, however, technological improvements and the promise of artificial intelligence offer much less relief. Expertise is still needed to determine which rules apply, which exemptions are available.
Vows to simplify the tax code are one of Ottawa’s most enduring refrains, echoing across decades of royal commissions, parliamentary committees and think tanks that have launched investigations into its twisted wiring.
They often return to strikingly similar diagnoses: broaden the tax base, reduce special preferences and make the system easier and cheaper to administer.
The 118th edition of the bilingual Income Tax Act, published in August 2026, is just about the size and weight of a breadbox.
With files from The Globe and Mail